


Reading the Appraisal Clause in a Nevada Property Policy
A plain-English walk through the paragraph that turns a stalled claim into a three-person panel.
Independent claim appraisal · Statewide
Your insurer accepted the claim, but the check won’t cover the repair. Nevada Insurance Appraiser builds an independent, line-by-line valuation of the damage and takes it through the appraisal process written into your policy.
The short version
Most underpaid claims are not denials. They are short: a tile roof priced as a patch, a smoke claim reduced to a wipe-down, a slab leak with no allowance for the floor. Nevada Insurance Appraiser exists for the gap between “covered” and “paid in full.”
When the appraisal clause is invoked, each side names an appraiser. As your Nevada Insurance Appraiser, we inspect the property ourselves, price every line for your area and defend that number in front of the insurer’s appraiser and, if needed, a neutral umpire.
Services
Twelve services built around one job: a valuation of your loss that holds up. Start with an estimate review, or bring us in after appraisal has been demanded.
We act as the appraiser you name after either side demands appraisal under your policy.
Learn more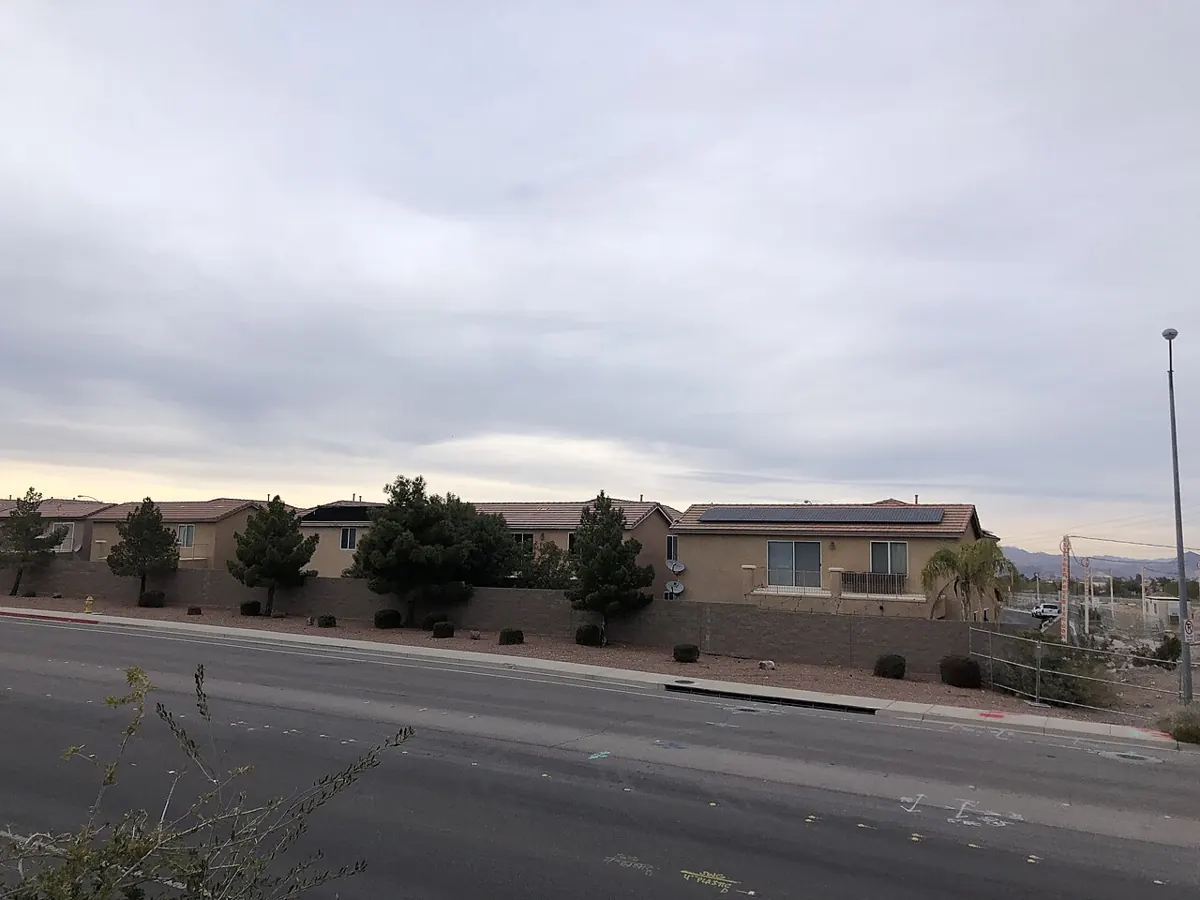
Houses, townhomes and condo units where the carrier’s estimate misses real repair costs.
Learn more
Retail, office, warehouse, multifamily and community association losses with large scopes.
Learn more
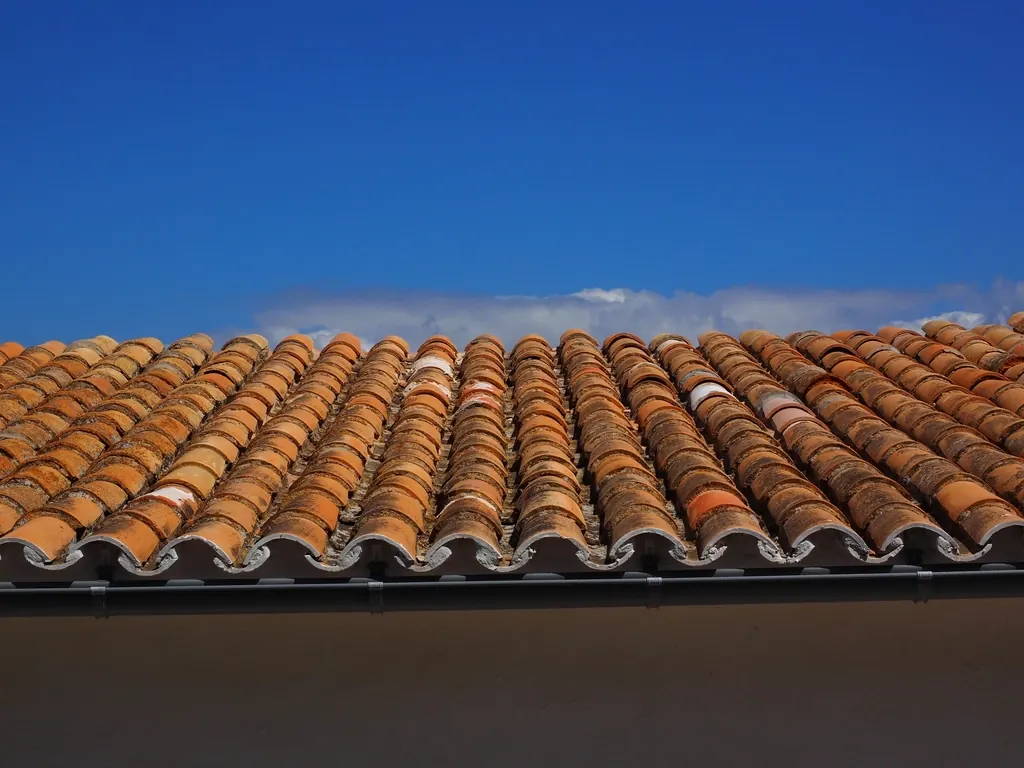
Concrete tile, clay tile, shingle and low-slope roofs damaged by hail, impact or storms.
Learn more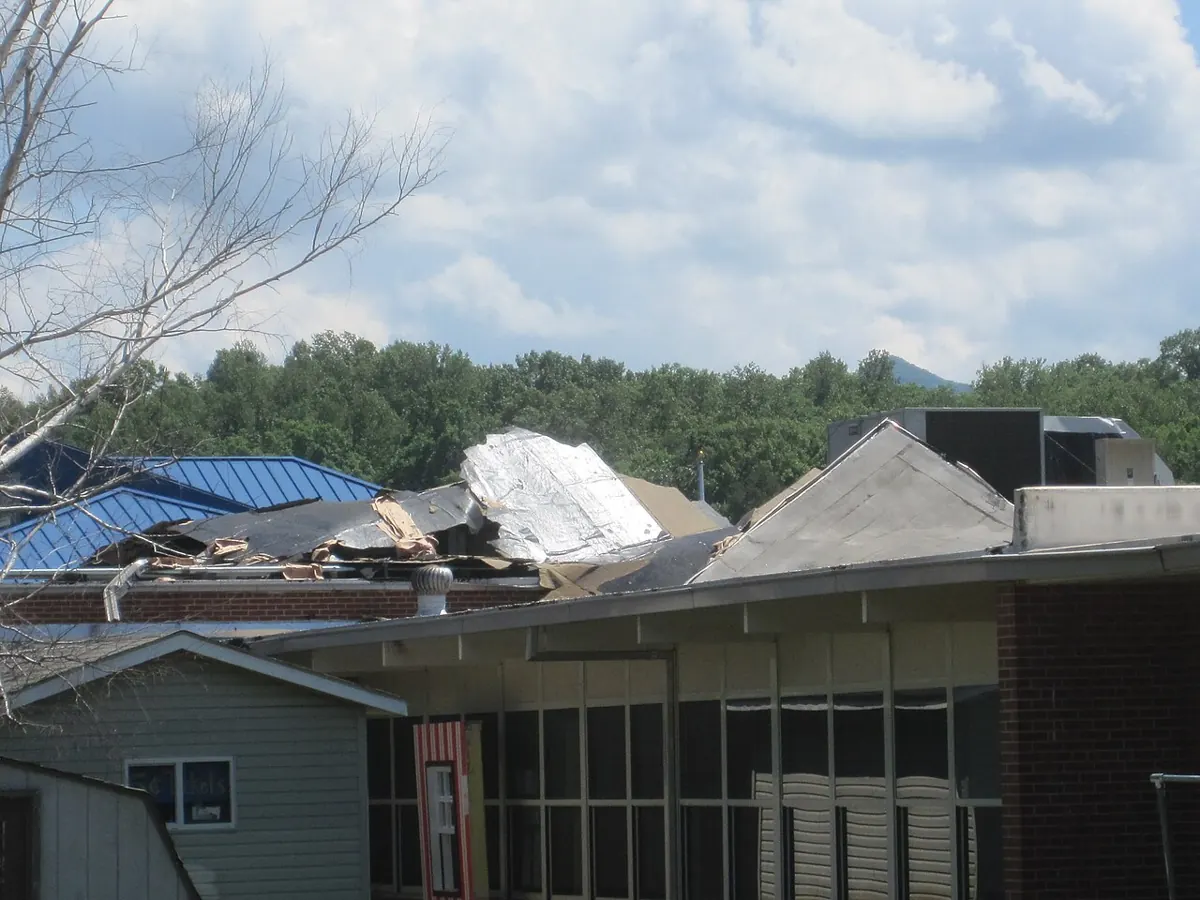
Downslope winds, microbursts and dust storms that lift roofing, topple walls and break glass.
Learn more
Summer monsoon storms and remnants of Pacific tropical systems bringing wind and heavy rain.
Learn more
Slab leaks, supply-line bursts, water heaters, frozen pipes and appliance failures.
Learn more
Structure fires, kitchen fires, electrical fires and smoke that reaches far beyond the burn area.
Learn more
Homes near the wildland edge damaged by flame, radiant heat, embers, smoke or ash fall.
Learn more
Heavy Sierra snow, ice dams, collapsed decks and burst pipes in Reno, Tahoe and Elko.
Learn more
A line-by-line read of the insurer’s estimate with a written list of what’s missing.
Learn more
Neutral umpire work for appraisal panels that can’t resolve every disputed line item.
Learn moreFour claim climates
A Nevada Insurance Appraiser has to know how a monsoon microburst in Henderson differs from a snow load in Incline Village or a smoke claim in southwest Reno, and how each one shows up in an estimate.
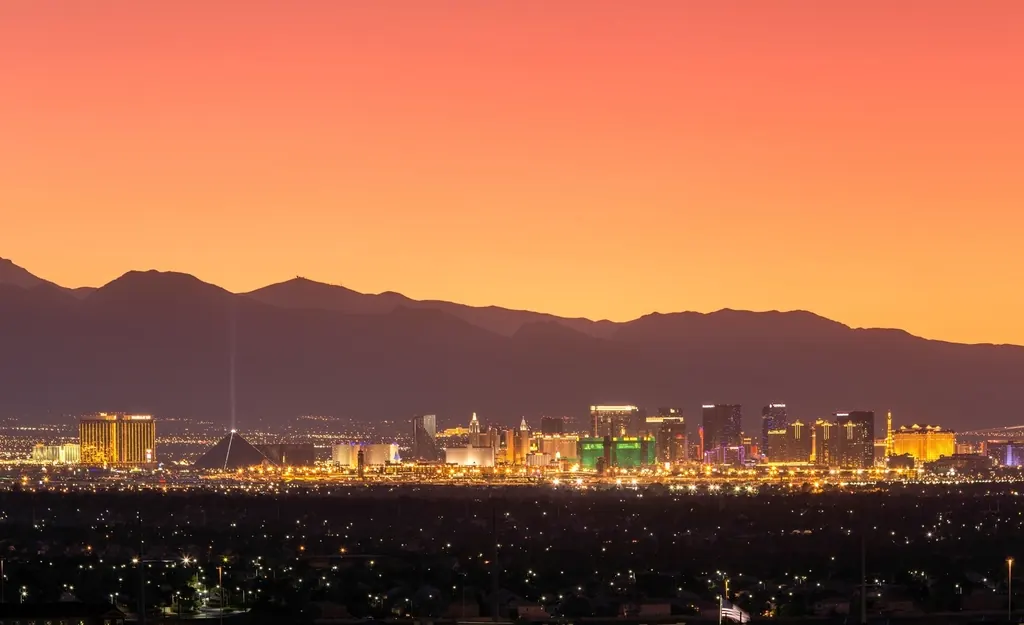
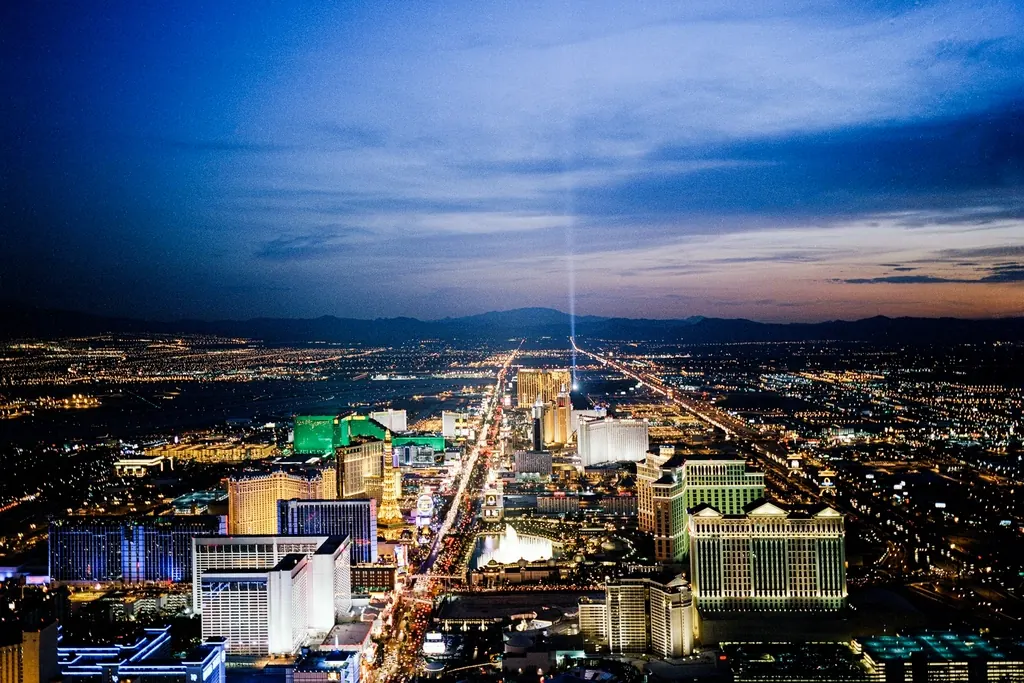
About three of every four Nevadans live in Clark County, most of them in stucco homes with concrete tile roofs built since the 1980s. Extreme heat ages roofing fast, very hard water corrodes plumbing, and summer monsoon storms bring sudden wind, hail and flooding.
Las Vegas · Henderson · North Las Vegas · Boulder City · Mesquite
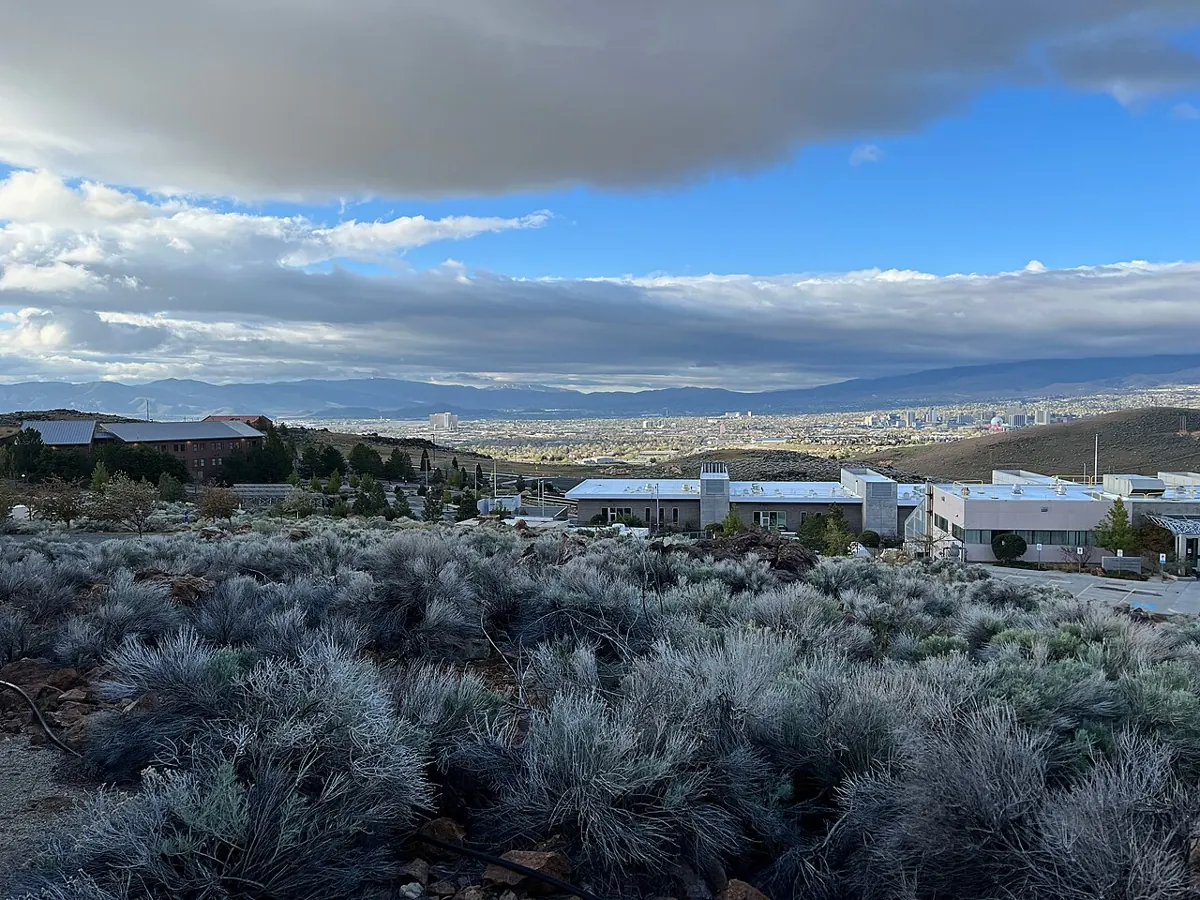
The Truckee Meadows sit where the Sierra meets the Great Basin. Foothill neighborhoods face wildfire, the Washoe Zephyr tests roofs every summer afternoon, and the Truckee River has flooded downtown Reno and Sparks more than once.
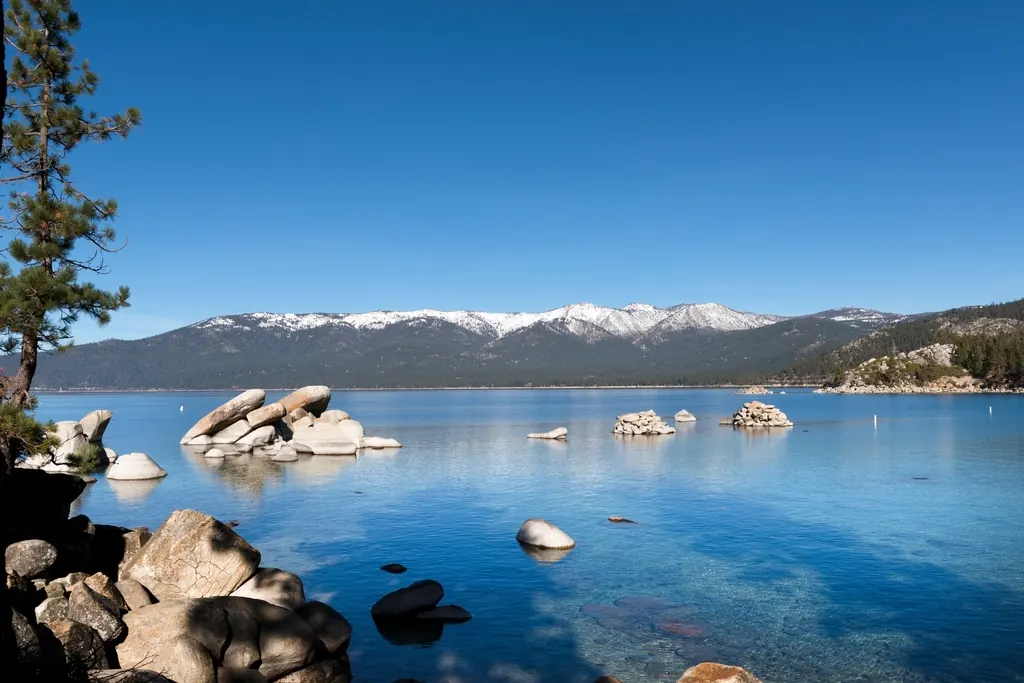
Nevada’s capital and the Carson Valley sit at the foot of the Carson Range; Lake Tahoe’s Nevada shore sits above them in heavy-snow country. Claims here involve fire at the wildland edge, winter snow loads and high-value mountain construction.
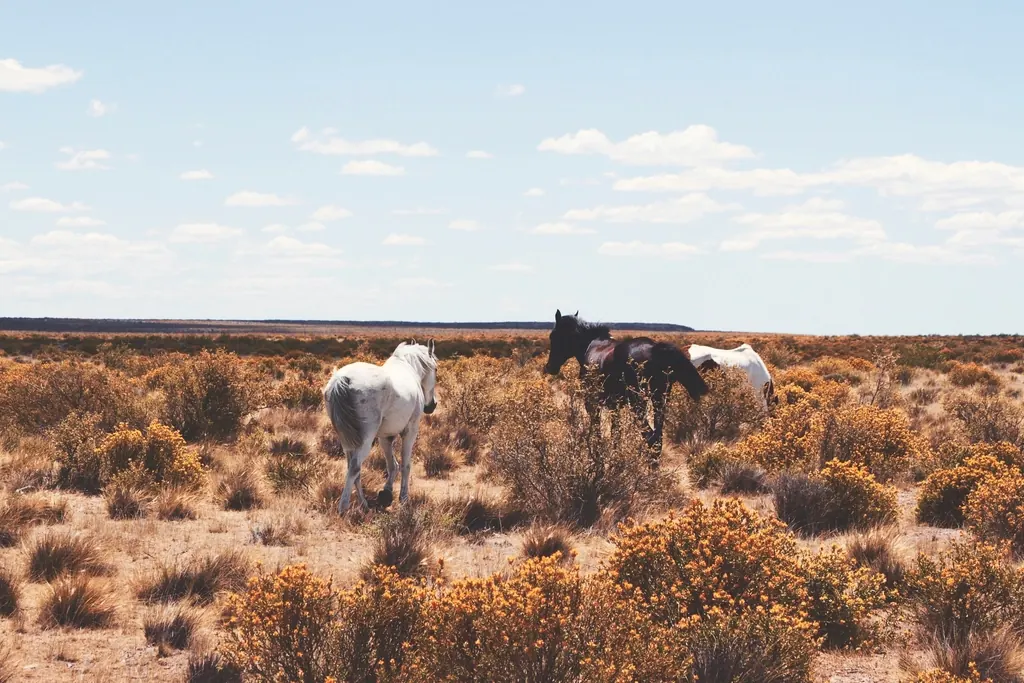
Most of Nevada’s land is open basin and range. In Pahrump, Elko and the towns between, homes sit on large lots with outbuildings and wells, winters can be brutal, and the 2008 Wells earthquake showed that the Great Basin can shake.
Quick check
Type in the two numbers you already have. If the difference is large, a call with a Nevada Insurance Appraiser makes sense. If it is small, a documented supplement request may close it faster and cheaper.
The full claim gap & fee estimator adds appraiser and umpire fees and shows your break-even point.
Open the toolkitThe process
The appraisal clause turns an open-ended argument into a defined process with a binding result. Here is how Nevada Insurance Appraiser moves a file through it.
We read your policy, the insurer’s estimate and your photos, then tell you plainly whether appraisal fits.
We inspect, measure and build a line-item estimate priced for your part of Nevada.
Appraisal is demanded in writing and we are named as your appraiser within the policy’s time frame.
We work line by line with the insurer’s appraiser. Most disputes narrow sharply here.
Anything left goes to a neutral umpire. Two signatures set the amount of loss.
Nevada’s loss record
Floods on the Truckee, monsoon storms in the Las Vegas Valley, fires along the Sierra front and earthquakes in the Great Basin. Every Nevada Insurance Appraiser file is shaped by this history, because insurers ask about prior damage and appraisers have to separate old from new.
Dates and descriptions are summarized from public records for context.
Free & private
Run the numbers before you pick up the phone. Every tool works in your browser; nothing is stored or sent.
CalculatorMeasure the disputed amount, project an award and find the break-even point after appraisal fees.
 Calculator
Estimate your first ACV check, the depreciation held back and the total once repairs are finished.
CalculatorTurn footprint and pitch into roof squares, waste, tile counts and the share of broken tile.
 Calculator
See a wind, hail or earthquake percentage deductible in dollars and compare it to a flat deductible.
 Planner
Turn your date of loss into dated milestones and download them to your calendar.
 Checklist
Twelve yes-or-no questions that score how ready your file is for an appraisal panel.
 Estimator
Build an illustrative smoke and ash cleaning scope after a wildfire or house fire.
Statewide
We work in every Nevada county. These are the communities where Nevada Insurance Appraiser handles claims most often.
Questions
Straight answers about how appraisal works, what it costs and when it is the wrong move.
We value property damage when you and your insurer agree a loss is covered but disagree on what it costs. As your appraiser we inspect, build an independent line-item estimate, work with the insurer’s appraiser and, if needed, present unresolved items to a neutral umpire.
A public adjuster manages and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question: the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
When coverage is accepted, you have the insurer’s estimate and the gap between it and your contractor’s number is meaningful, generally more than about 10% or several thousand dollars.
Yes, on the amount of loss, once any two of the three panel members sign. That is why documentation matters so much before appraisal is demanded.
Each side pays its own appraiser and usually half the umpire. We put our fee in writing before any work starts, and the first conversation is free.
Yes. We work in all 16 counties + Carson City, including Carson City, the Carson Valley, Lake Tahoe, Pahrump, Mesquite and Elko.
Field notes
Practical guides from Nevada Insurance Appraiser on policy wording, documentation and Nevada-specific claims.
A plain-English walk through the paragraph that turns a stalled claim into a three-person panel.
Concrete tile is everywhere in the Las Vegas Valley. Here is why tile roof claims are disputed so often, and what to document.
Your home didn’t burn, but it smells like it. What to document and why the cleaning scope is usually the fight.
Before you sign off
A short review now can keep you from accepting a settlement that won’t cover the repair.
Start a conversation
Tell us what happened and what the insurer offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing. No pressure, no obligation.
